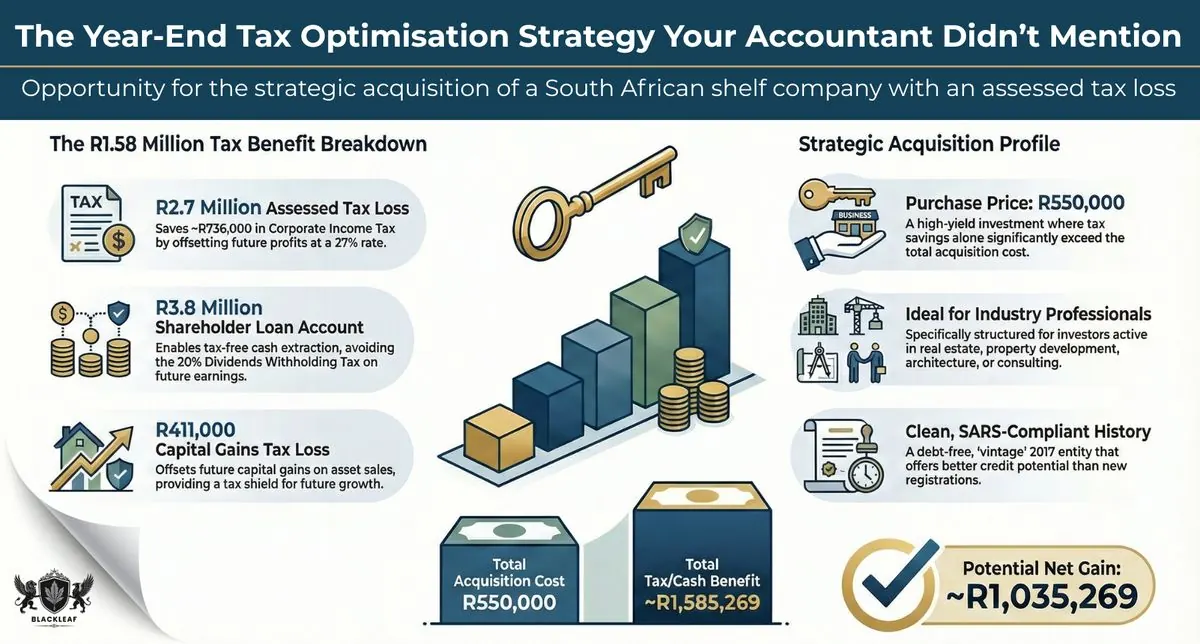
Unlocking the hidden value of a shelf company with an assessed tax loss
As the February financial year-end looms on the South African corporate calendar, a familiar anxiety sets in. For profitable businesses, it is the season of provisional tax payments - a significant cash outflow that often feels like a penalty for success.
Most advice you receive right now is standard fare: contribute more to employee benefits, pre-pay legitimate business expenses or accelerate asset write-offs. However, for the sophisticated corporate strategist, there is a more potent, often overlooked lever: Strategic M&A Tax Arbitrage. This is not about buying a competitor for market share. It is about acquiring a specific type of corporate asset to leverage as a tax-efficient launchpad for your next division.
Here is the counter-intuitive strategy that transforms a paper loss into a future gain, and why a specific opportunity currently on the market might be the secret weapon your portfolio needs.
The Concept
In the world of accounting, a loss is usually a sign of failure. However, under South African tax law, a tax loss can be an asset. When a company’s deductible expenses exceed its income, it generates an Assessed Loss. SARS allows the company to carry that loss forward indefinitely. Crucially, any future profits earned by this company can be set off against that historical loss.
The Rules
While this strategy is powerful, its execution requires expertise and precision. SARS prohibits the acquisition of dormant shelf companies solely for tax relief and regulates the rate at which such a benefit can be utilised. For compliance, certain requirements must be fulfilled:
The Trade Requirement (Section 20): To utilise a tax loss, SARS requires active trade. A dormant company forfeits this asset, so one must reactivate business operations immediately upon acquisition.
General information only. It is not legal, tax or investment advice. Speak to a qualified adviser before you act on it.